

“He who laughs last, laughs best.”
— Proverb
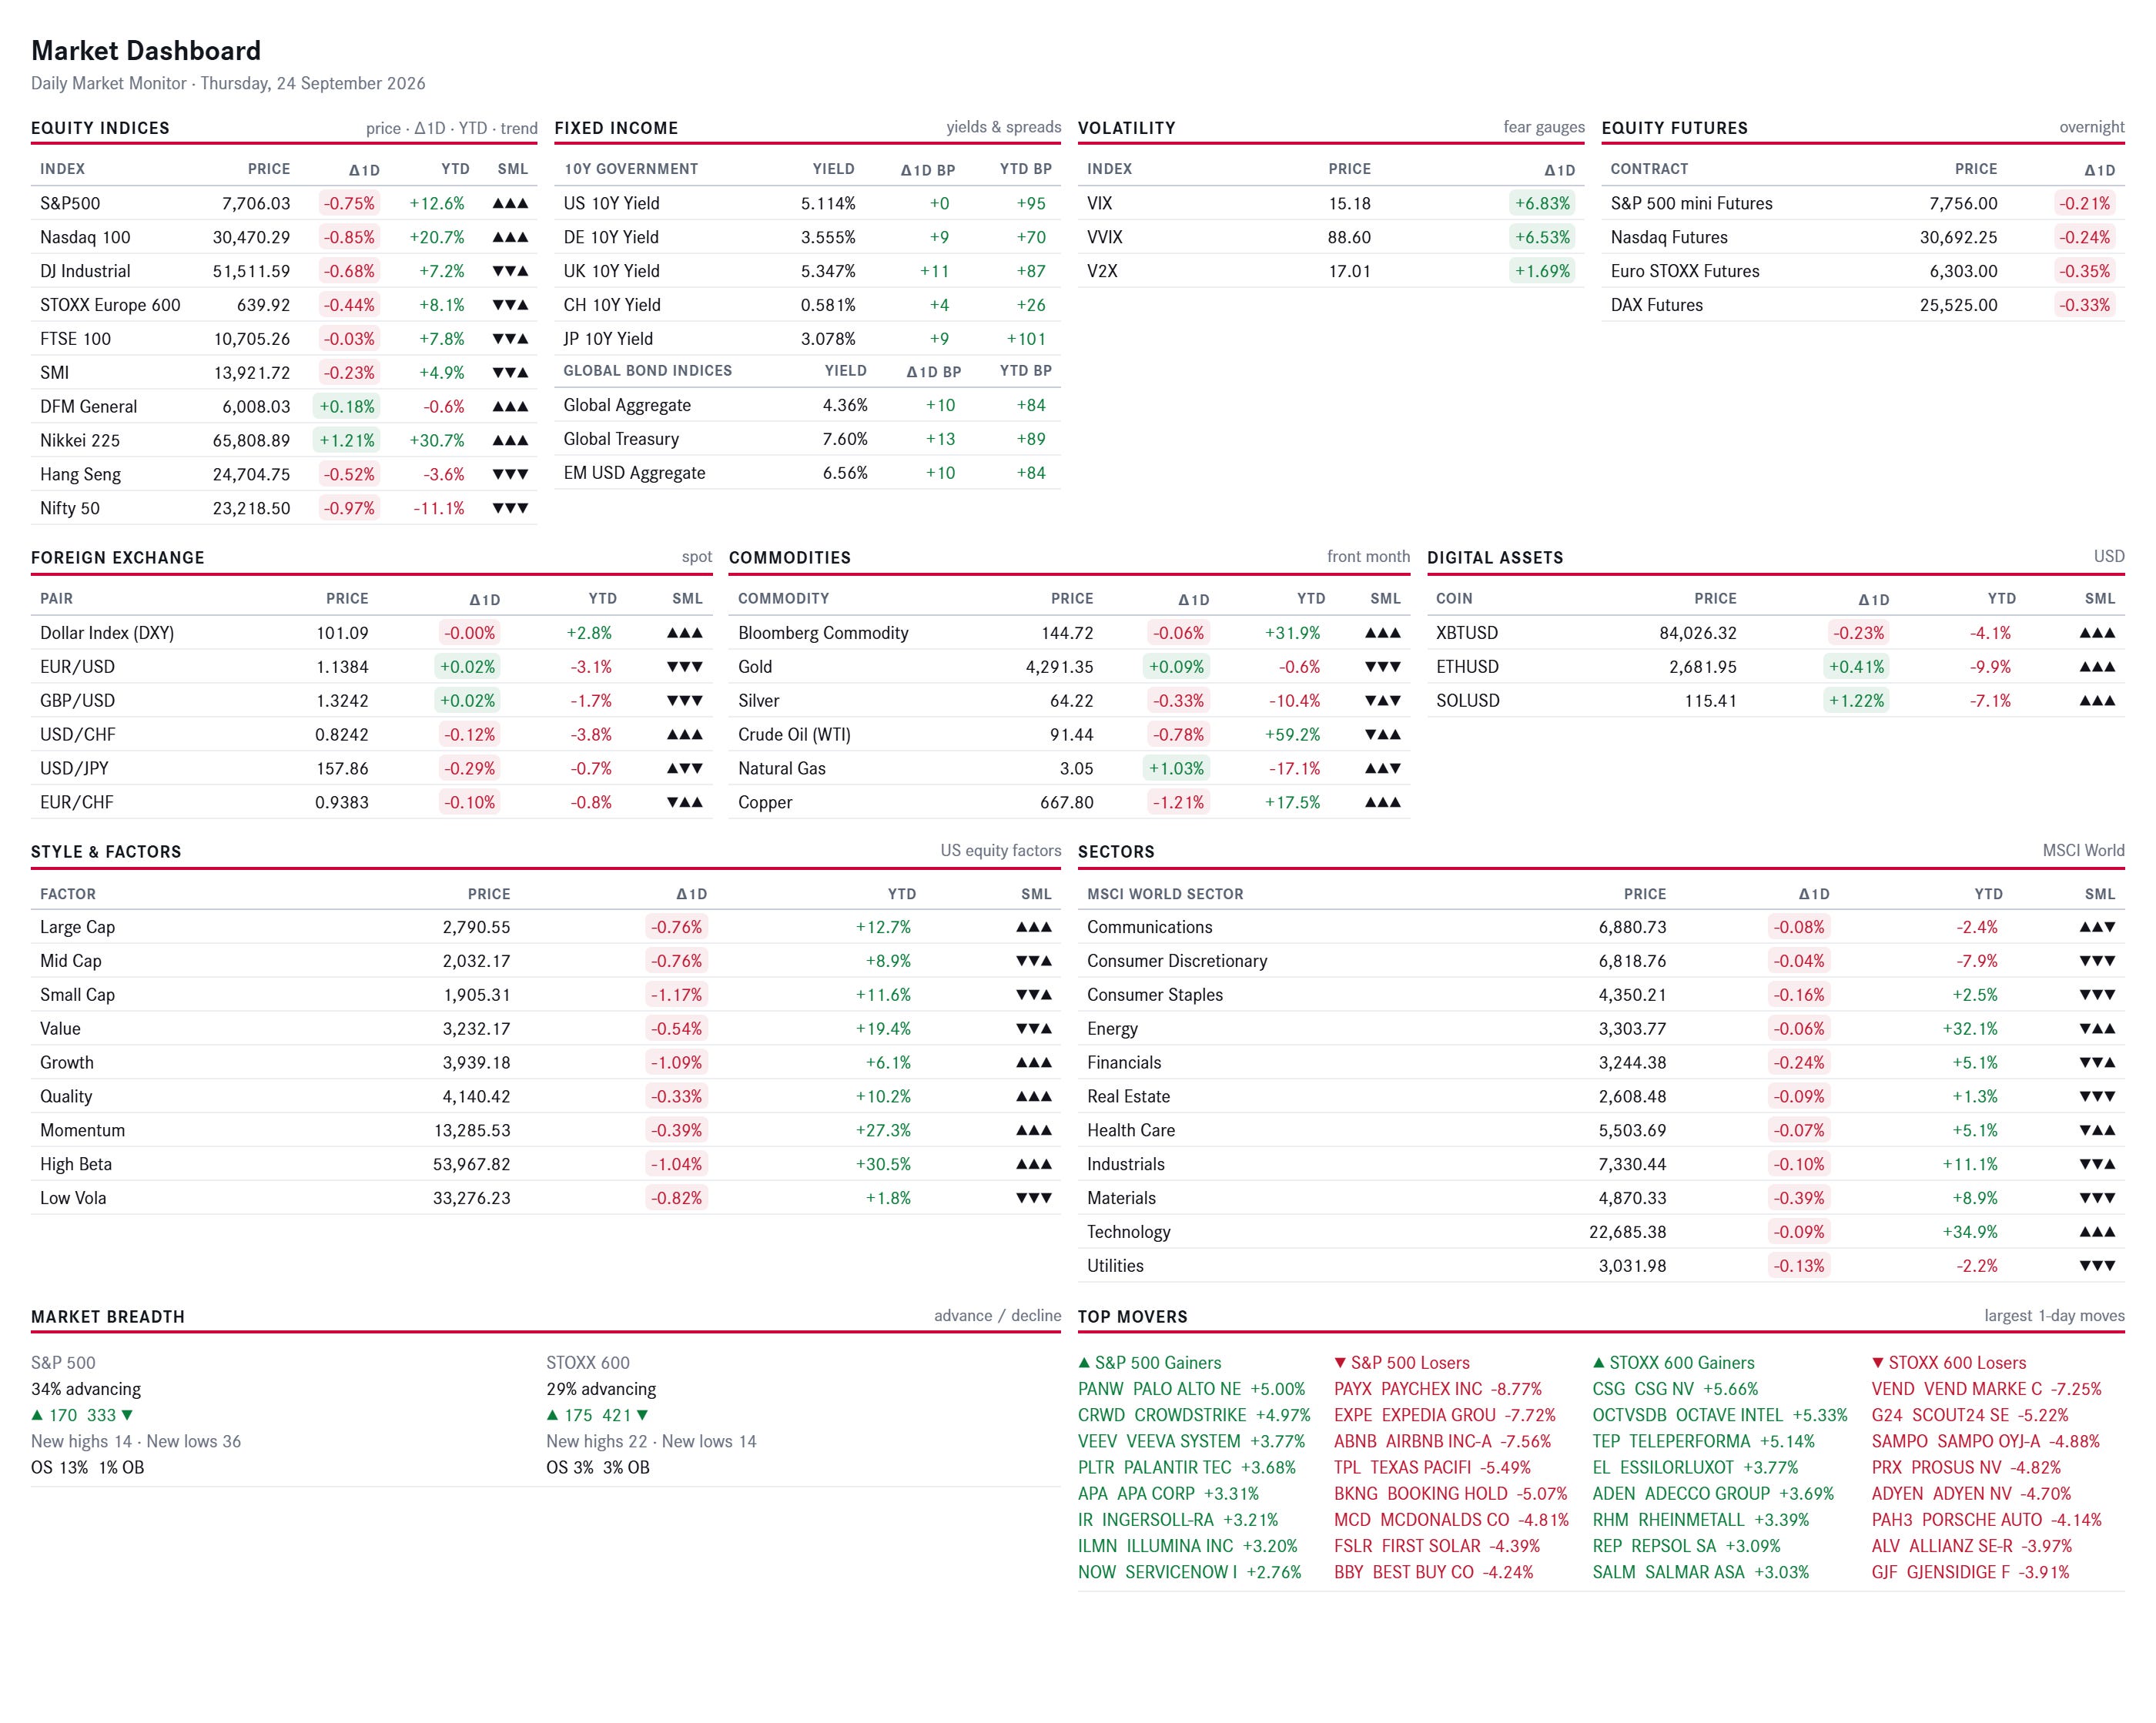
For the full dashboard, please click on ‘Download’ below:

Even though there is plenty to write about, I will need to keep it short and mostly factual here today, as I am heading into an 8 a.m. meeting in a few minutes.
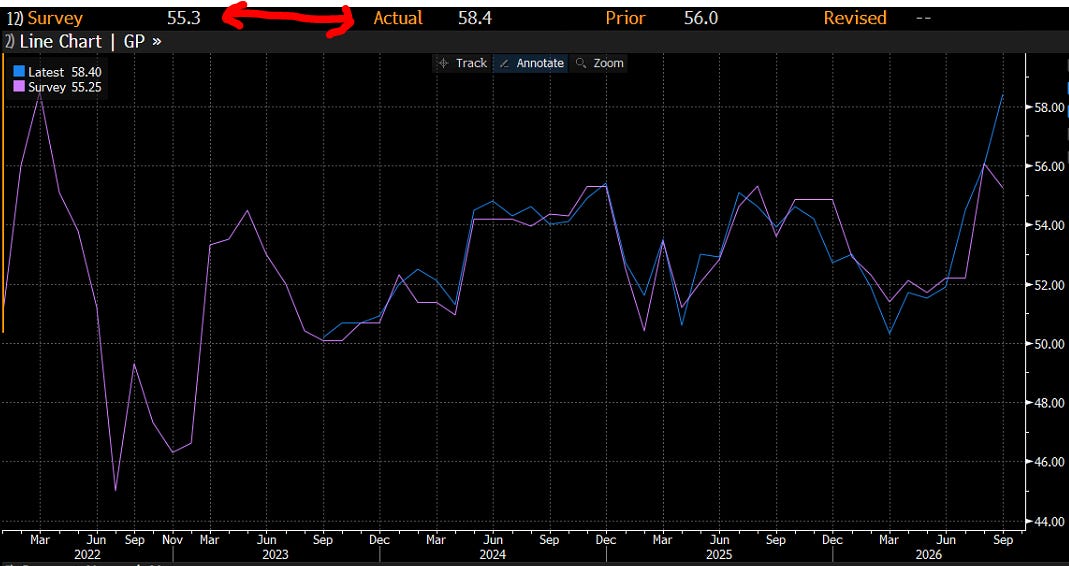
As today’s subtitle of The Daily Q suggests, FOMC Chairman Kevin Warsh’s decision to hike interest rates and keep an underlying hawkish tone was somewhat vindicated yesterday, as the S&P’s PMI Composite showed the highest post-pandemic reading and came in well above economists’ consensus:
(US) Interest rates shot higher, with the 10-year reaching at 5.13% its highest reading since 2007:
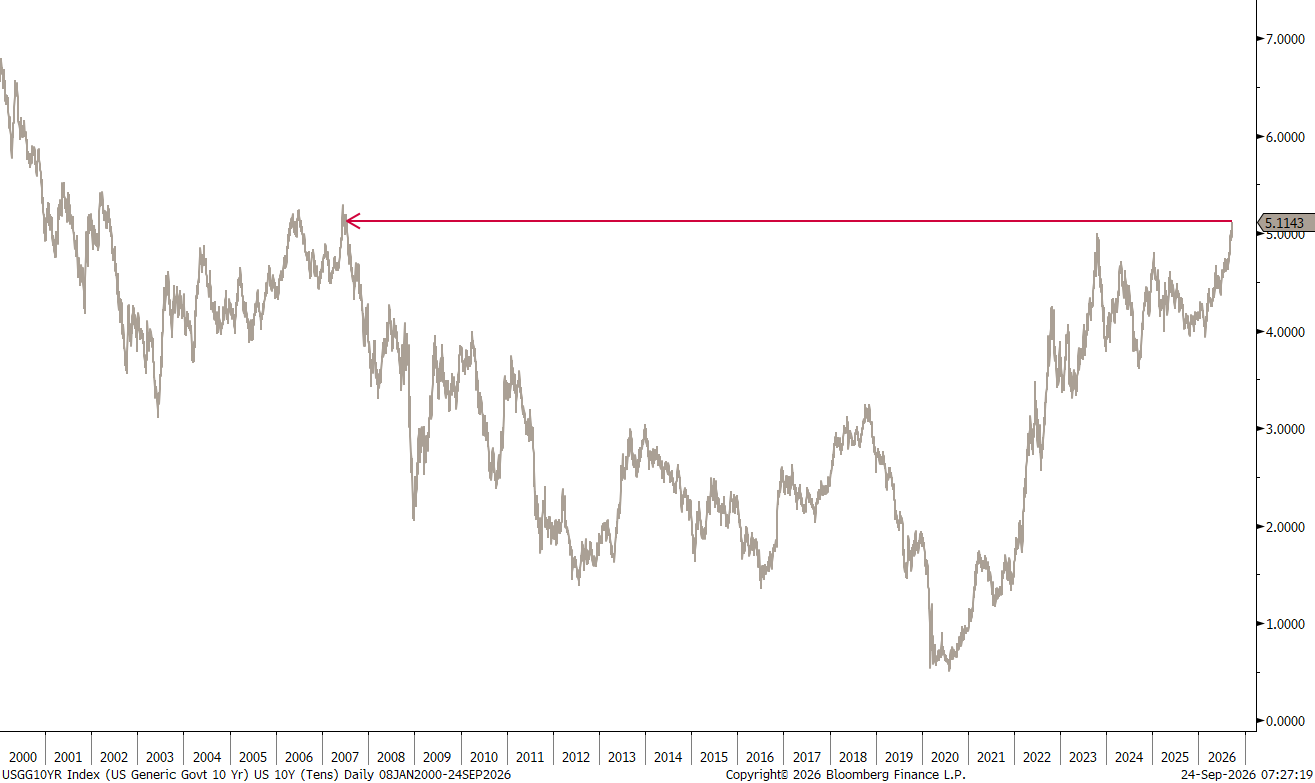
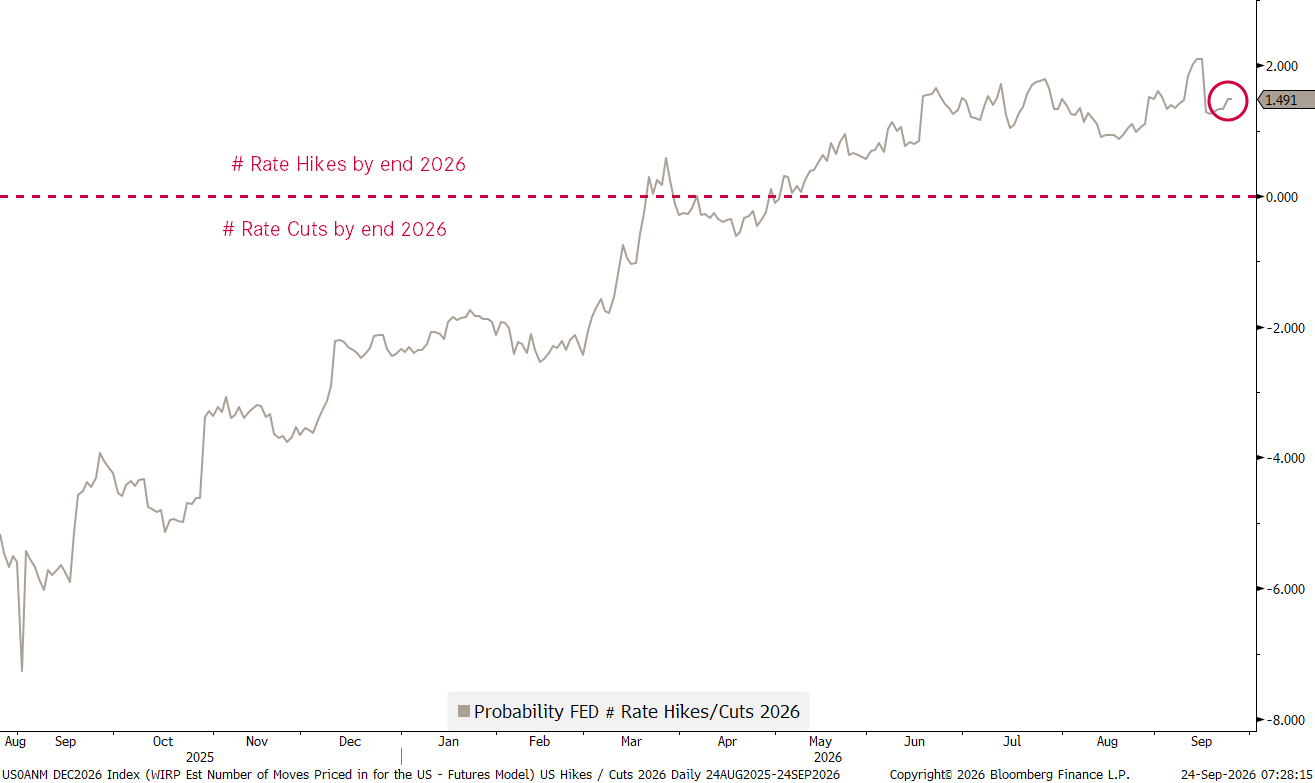
Of course, did expectation for further rate hikes as implied via futures markets also increase again:
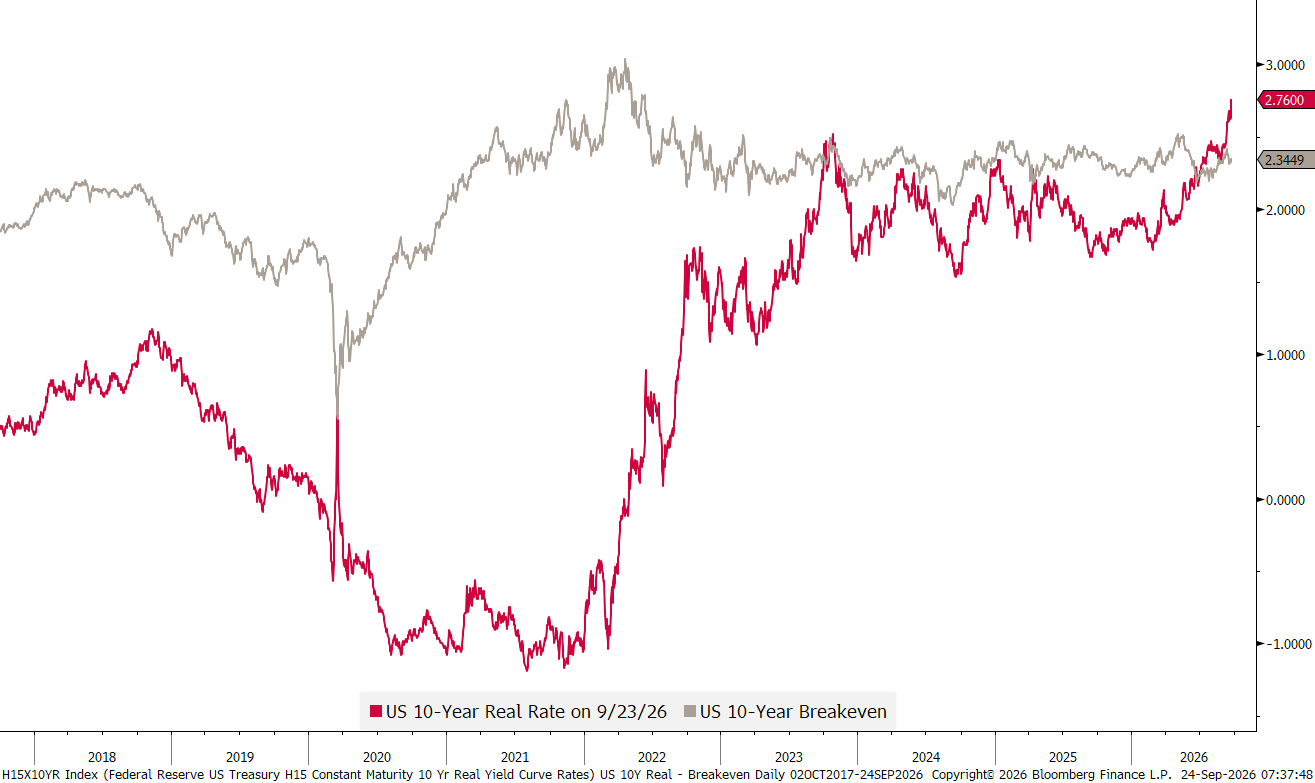
HOWEVER, and this is important, the rise in yields yesterday came on the back of strong economic growth expectations (remember, PMI is soft data, i.e. survey based, not hard data) and not from increased inflation expectations.
This is not least expressed via the following chart, which shows that Real 10-year yields (nominal minus inflation) are now higher then 10-year inflation breakevens, i.e. market-based inflation expectations (nominal yields - TIPS yield):
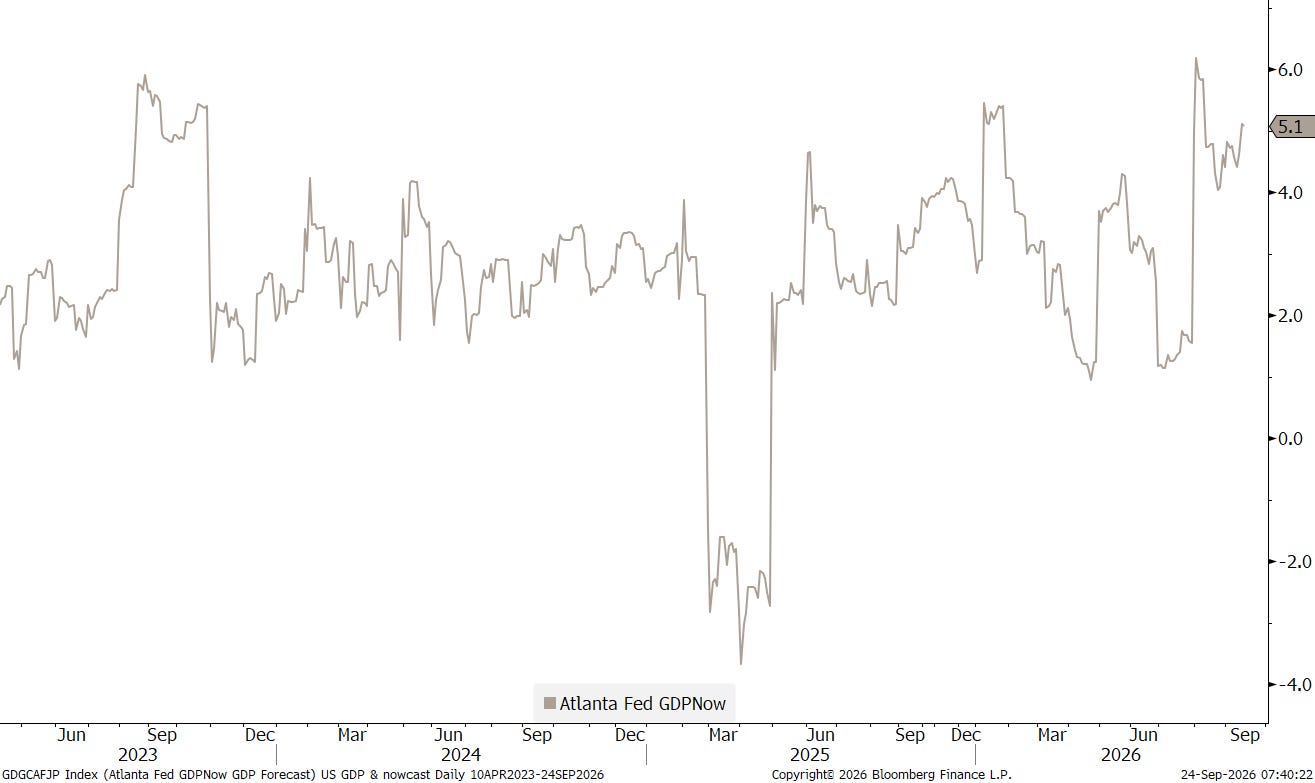
BTW, we should have known, that strong economic readings were lying ahead. After all, the Atlanta Fed’s GDPNowcast indicated a growth rate of 5.1% recently:
Equity markets’ knee-jerk reaction was to focus on the prospect of higher Fed Fund rates first, rather then the astonish growth and the major benchmark indices retreated close to 1%.
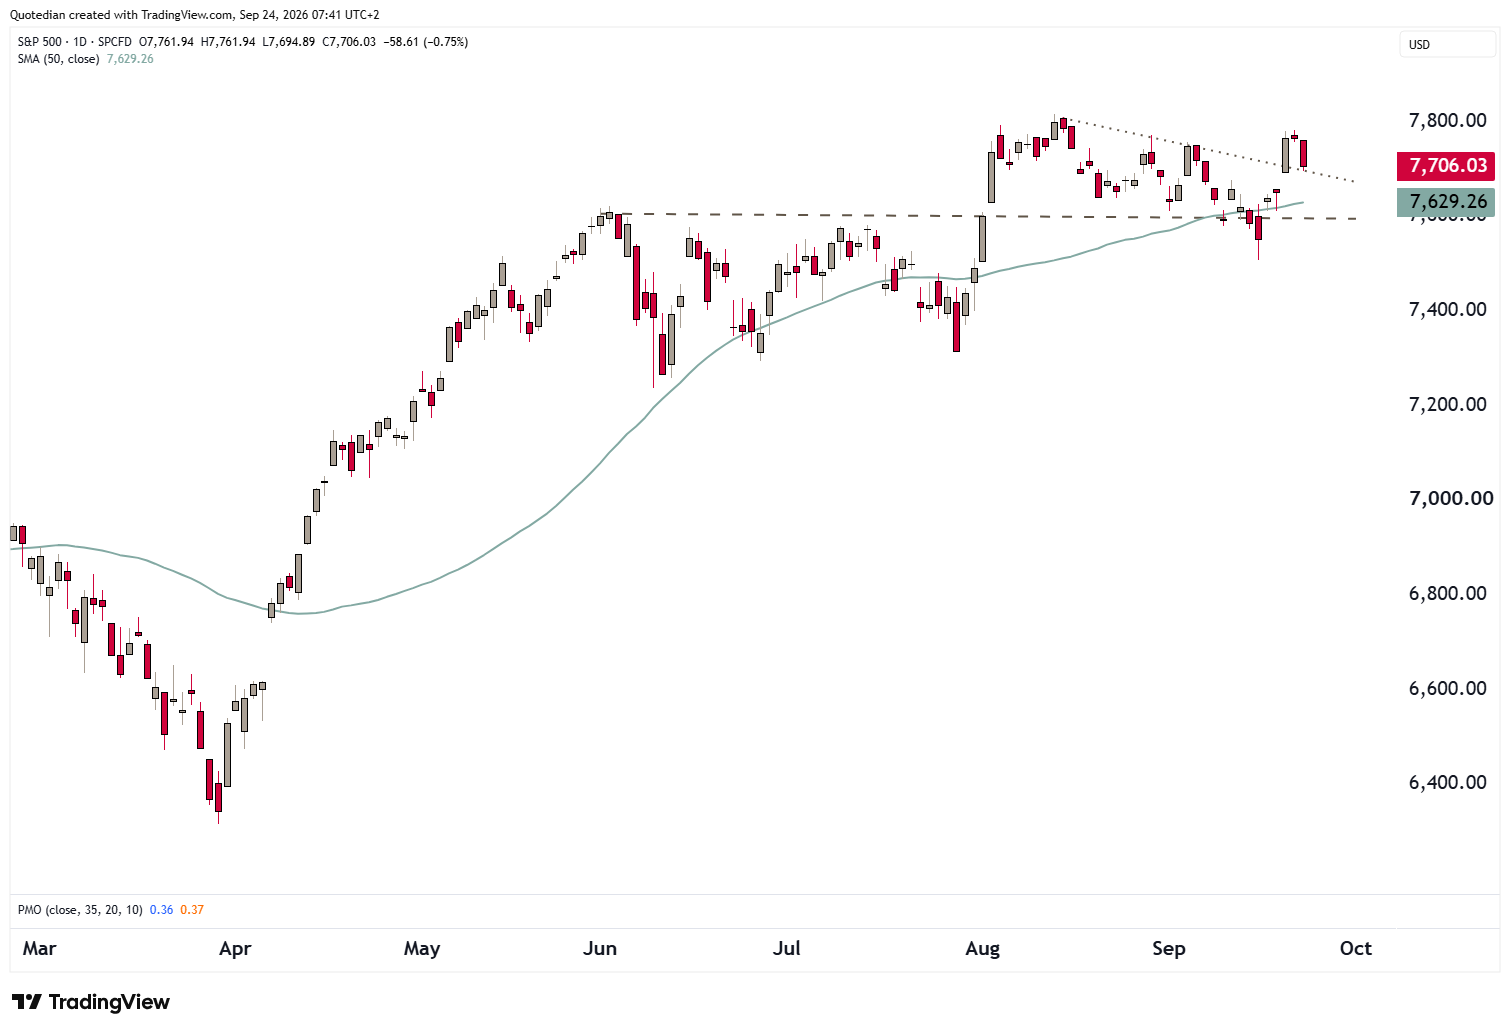
Here’s the S&P 500 for example, where, if the current level can hold today, not all hope is lost for the bull trend to continue:
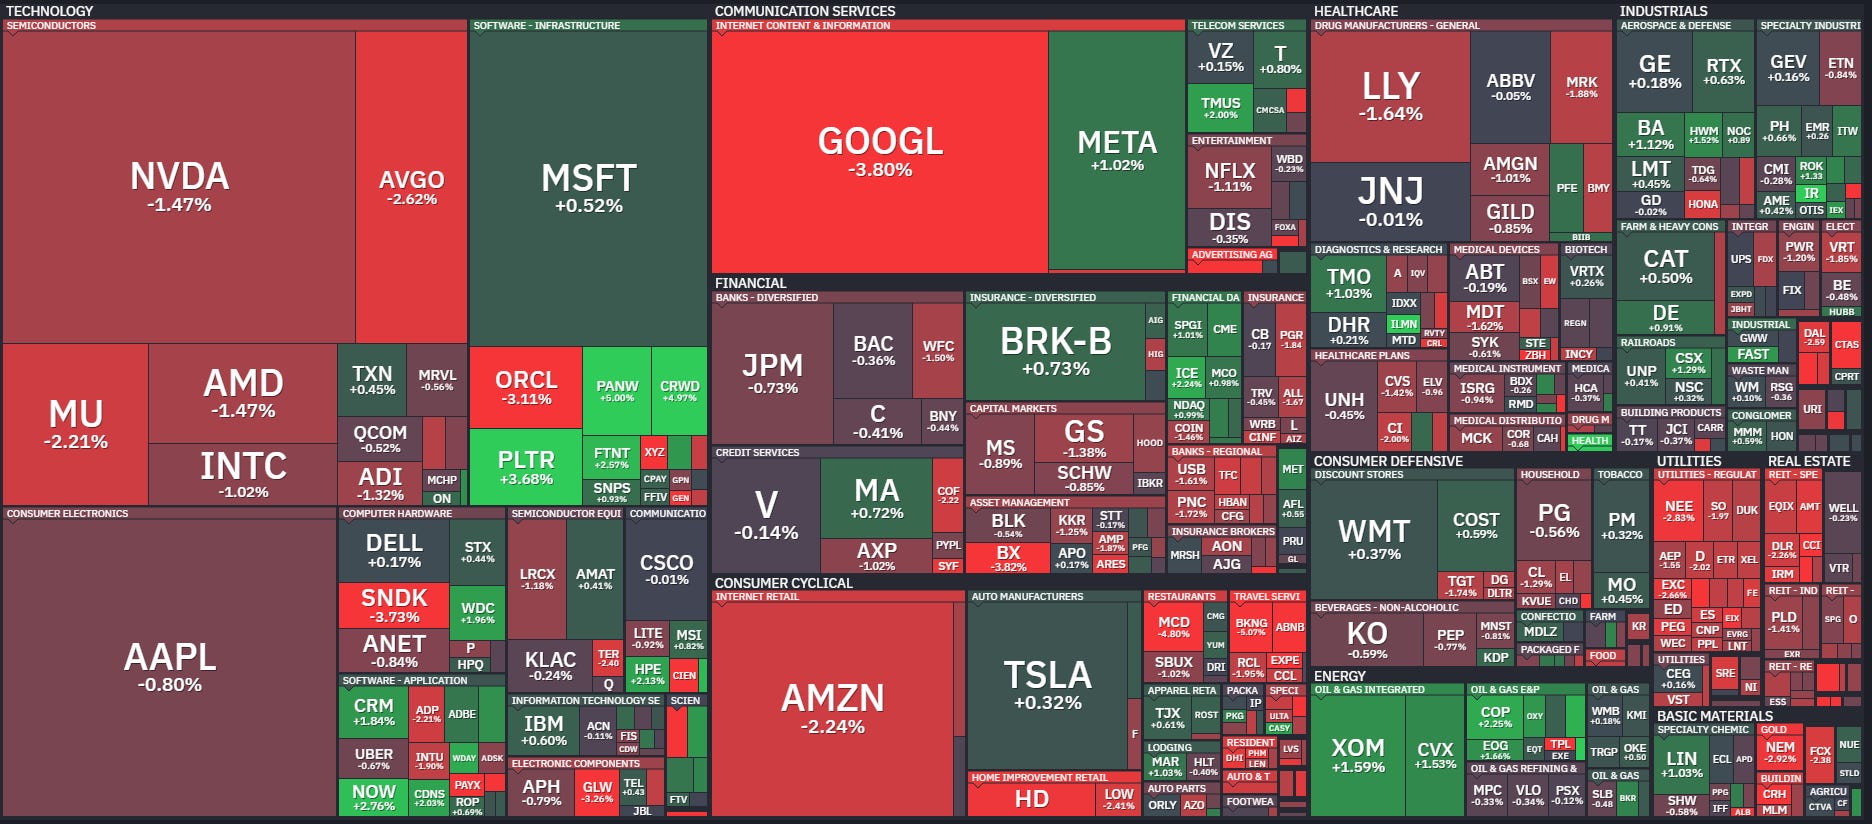
Importantly, similar to the previous two sessions, when markets headed higher but participation was, well, meh, in yesterday’s “sell-off”, the loser-to-winner ratio was also only about 3:2.
And from a first glance at the market map, it feels like the winners of the previous two sessions were the losers yesterday and vice versa:
Asian markets are mixed this morning, with the Nikkei being one of the advancers (+1%). This index is about to nullify the trend reversing shoulder-head-shoulder pattern we have previously discussed with a move above the dotted line:
And as we know, there is nothing as bullish as a failed bearish pattern 😜
What else?
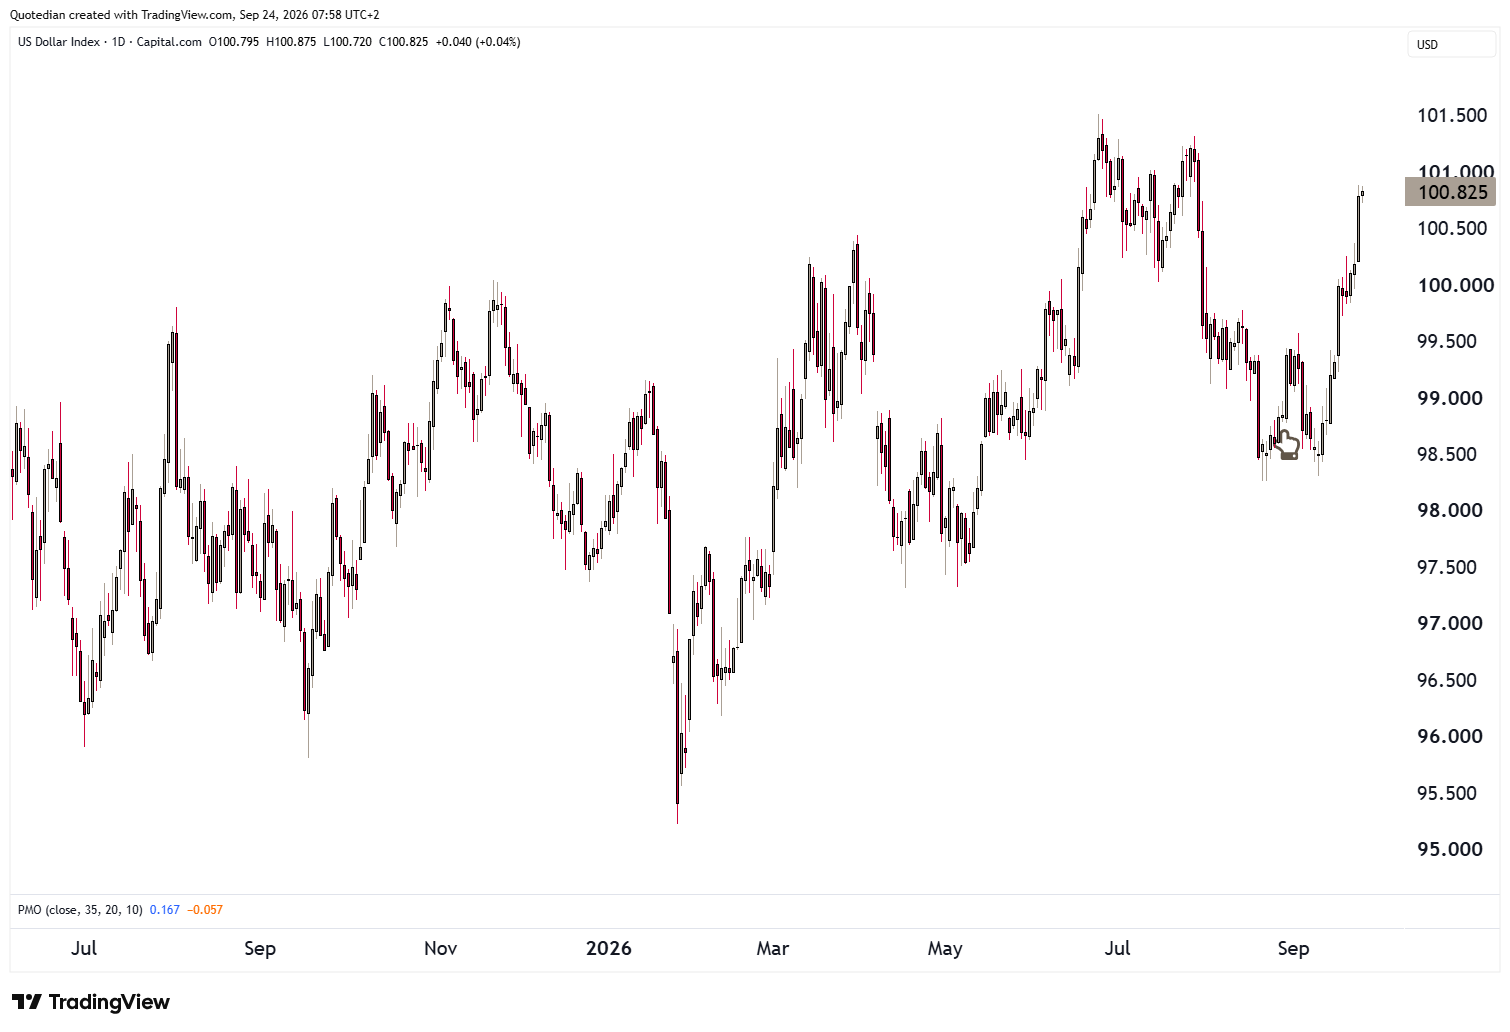
The US Dollar gained on the prospect of higher US rates, with the US Dollar Index closing in on the July highs and hence endangering our bearish outlook once again:
Dollar up probably means Gold down:
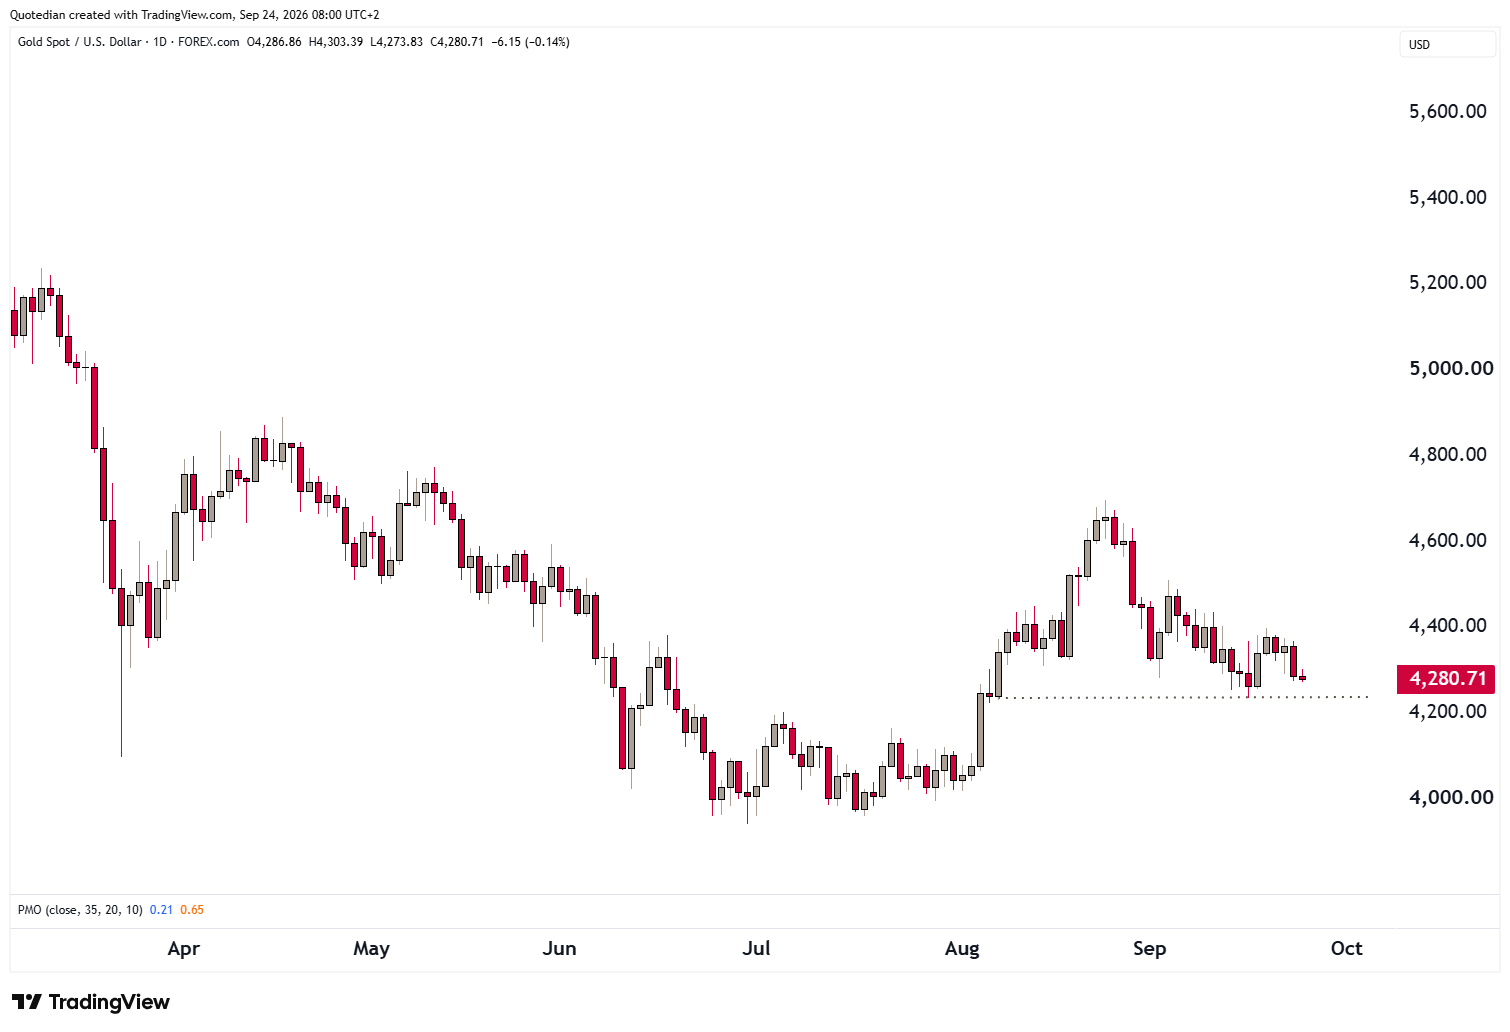
Indeed! Watch that support at 4,230 (dashed line) closely.
That’s all for today - have a great day, and,
May the Trend be with You!
André
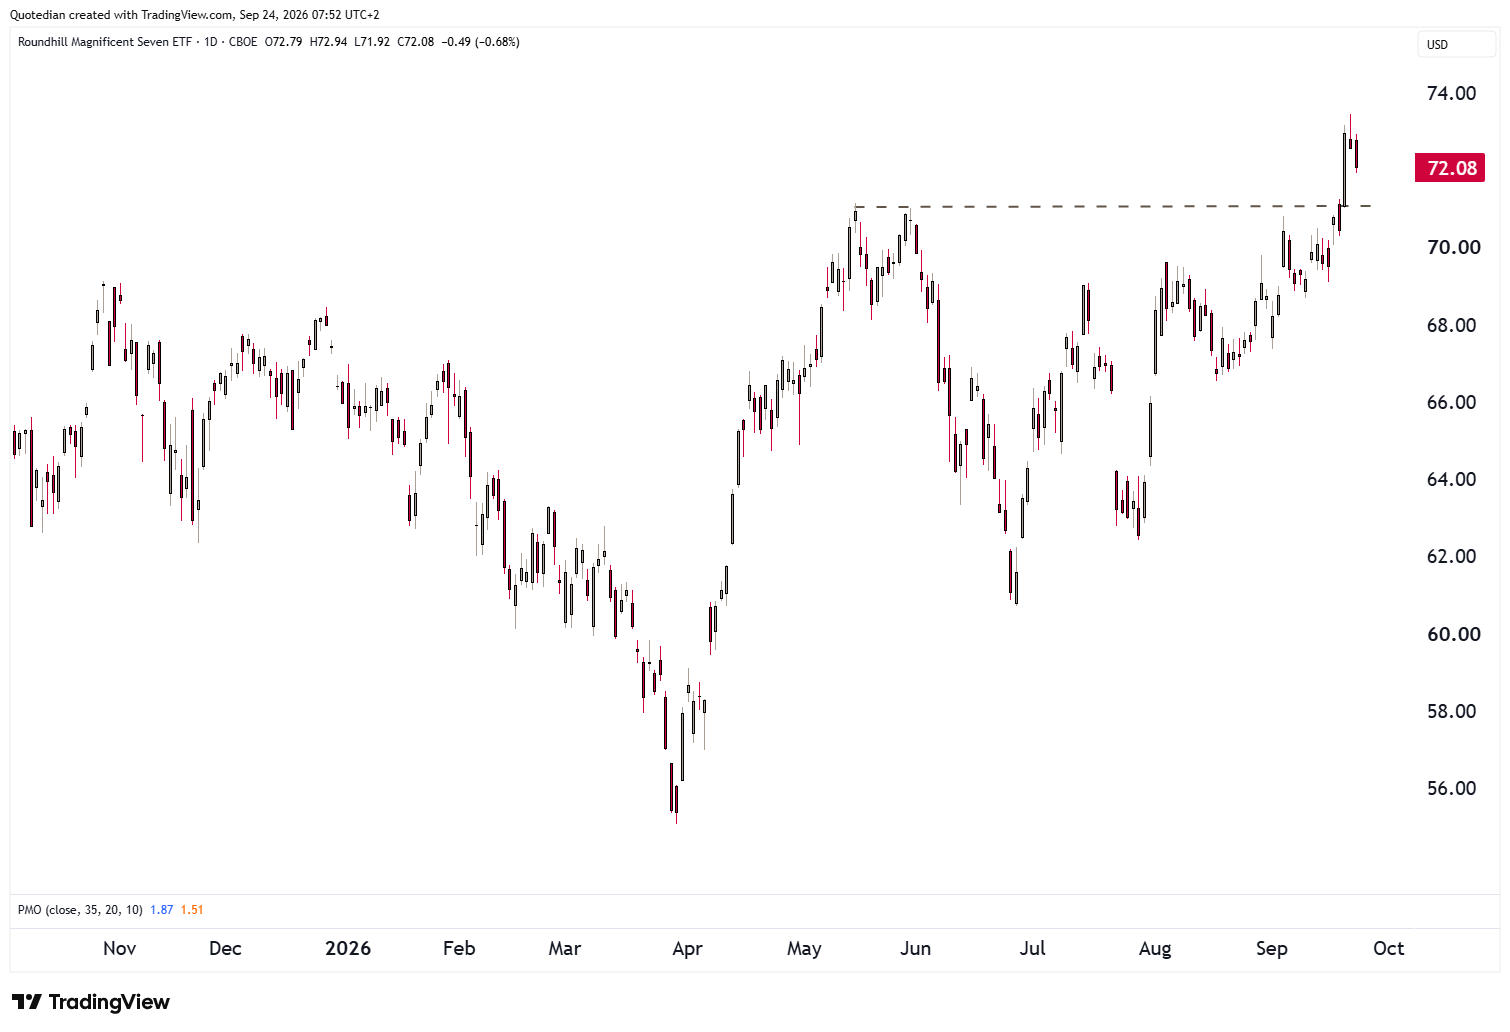
The Roundhill Magnificent Seven ETF, which tracks the performance of the … well, you know … showed a nice, clean break out of its multi-month consolidation pattern, not least on the back of a very strong performance by Meta:
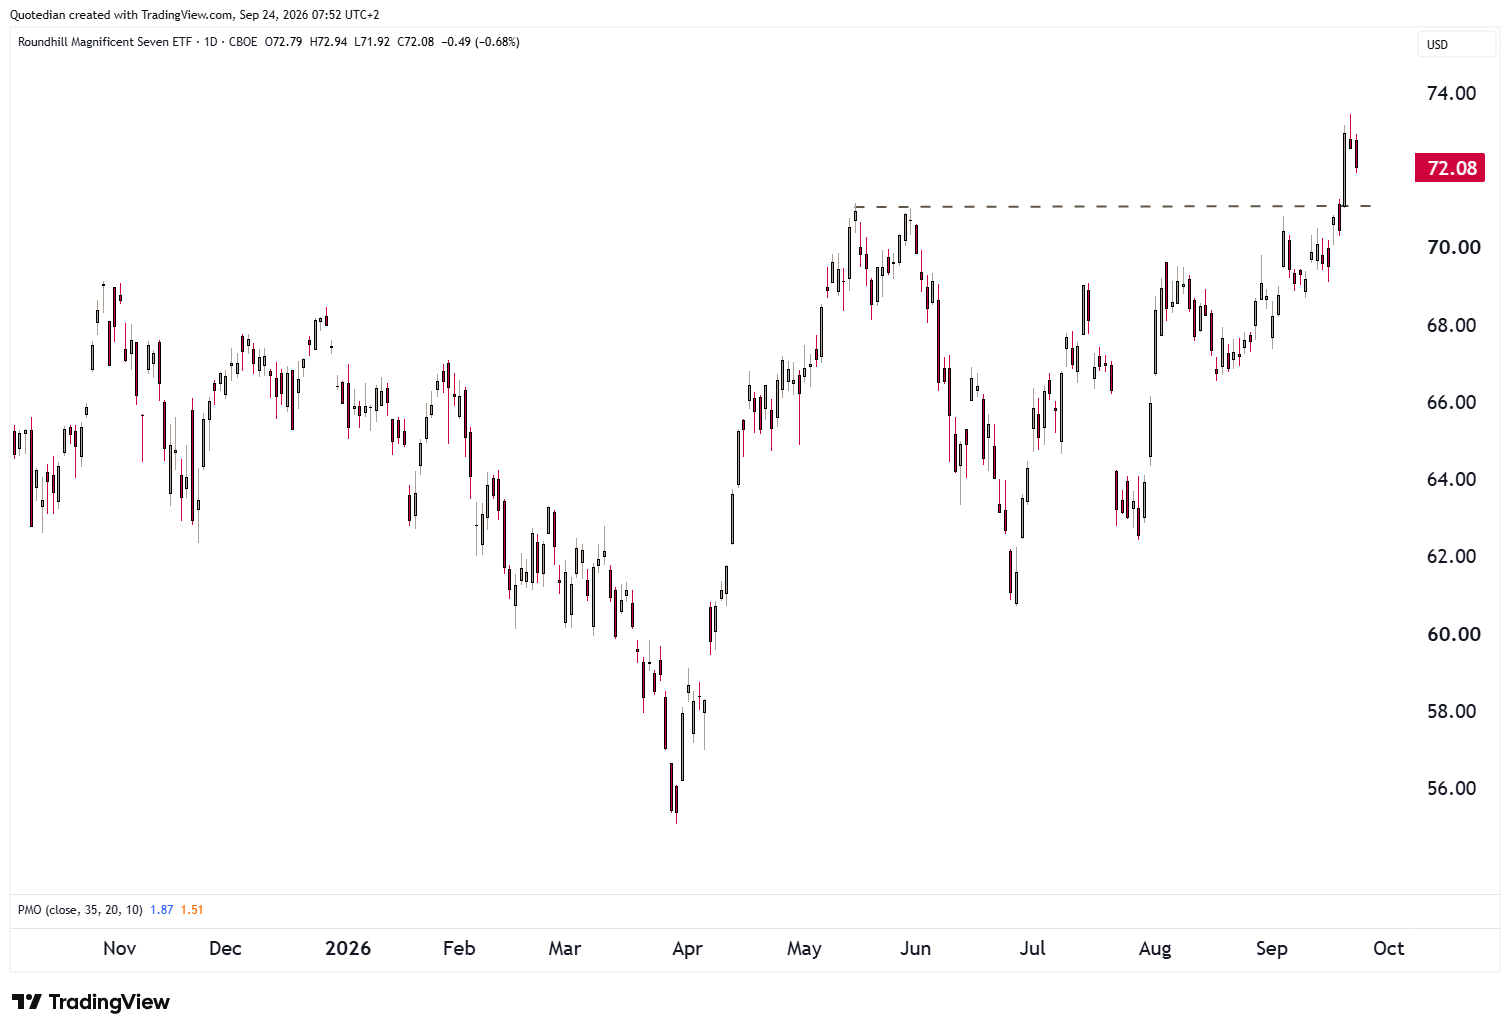
That previous resistance at roughly $71 has now turned support and may become a major testing ground for the current short-term bull run of the overall stock market to continue.
Stay tuned …
Everything in this document is for educational purposes only (FEPO)
Nothing in this document should be considered investment advice
Investing real money can be costly; don’t do stupid shit
Leave politics at the door—markets don’t care.
Past performance is hopefully no indication of future performance
The views expressed in this document may differ from the views published by NPB Neue Privat Bank AG